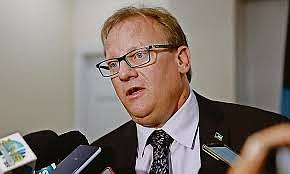
Ryan Pinder KC
By ANNELIA NIXON
TRIBUNE Business Reporter
anixon@tribunemedia.net
THE BAHAMAS was yesterday urged by a former attorney general to centralise financial services sector regulation and compliance into a single reporting portal to reduce duplication, improve efficiency and strengthen the jurisdiction’s international reputation.
Ryan Pinder KC told the Nassau Conference on financial services that the Government should consolidate the industry’s various compliance functions - currently spread across multiple agencies including the Central Bank, Securities Commission, Compliance Commission and Ministry of Finance - under one authority.
He warned that the existing fragmented system is placing unnecessary pressure on both regulators and the private sector. Mr Pinder’s proposal comes as The Bahamas prepares for the fifth-round evaluation of its anti-money laundering, counter-terrorist financing framework and anti-financial crime defences by the Caribbean Financial Action Task Force.
Mr Pinder said the compliance landscape has become increasingly complex over the past decade, contributing to higher costs, client frustration and operational inefficiencies across the sector.
“I think the assault on financial centres for reasons that may not be legitimate has caused, both from a government point of view and having to pass a regulatory framework and frankly, regulator point of view and having to enforce those, but more so on an industry point of view, we all know in the last 10 years what our compliance departments have evolved into,” Mr Pinder said.
He said compliance functions have increasingly become centred on preventative regulation, with financial institutions facing growing obligations while trying to maintain efficient service for clients.
“The fact of the matter is, it has resulted in more inefficient business in our space. It has resulted in more client frustration in our space, and it has frankly resulted in more fear from our industry,” Mr Pinder said.
He argued that The Bahamas’ relatively small size makes it particularly difficult for both the Government and the private sector to keep pace with the rapid evolution of international standards.
“Certainly, I can speak on behalf of my experience in government in trying to develop the capacity from a government point of view to keep up with the constant changes and evolution of these standards,” Mr Pinder said. “But I know that it is easily the same, if not more so, within industry in a small country trying to serve our clients the best we can.”
Mr Pinder said the Government should therefore examine a centralised model for compliance rather than continuing with multiple agencies and reporting channels.
“One thing that I think should be considered is the ability of government to keep pace with the changes and the obligations of international compliance functions,” Mr Pinder said. “It’s a challenge in capacity. It’s a challenge in resources.”
He said financial services firms currently have to navigate several reporting channels and agencies responsible for different aspects of compliance.
“I’ve always thought that the right approach, and I certainly think today the right approach, is more of a central approach,” Mr Pinder said. “And in my opinion, I think the Government should really look at developing a Compliance Authority.”
He proposed that the authority bring the various financial services compliance functions under one umbrella and establish an integrated digital reporting system. Mr Pinder said the current fragmented structure could undermine the sector’s ability to demonstrate efficiency and consistency internationally.
“The fragmented approach to compliance functions, I think, is doing a disservice to the industry, and I think it’s doing a disservice to our reputation,” Mr Pinder said. “I would really like to see us move towards an integrated compliance authority on behalf of government.
“I think the industry deserves that. I think the industry would welcome almost like a single portal or a single point of contact on all of these different compliance functions.”
The proposal was echoed by Niekia Horton, chief executive and executive director of the Bahamas Financial Services Board (BFSB), who said the sector should look at compliance through a more integrated and co-ordinated lens.
“We really need to start to look at this issue of compliance from an integrated lens, from a co-ordinated lens, because it’s difficult when you have different entities acting for the same thing on three or four different forms,” Ms Horton said.
She said industry’s concerns about compliance are not about avoiding its obligations, but about finding ways to meet them more efficiently.
“When the industry begins to express concerns, it’s not from a place of not wanting to comply or just wanting to complain,” Ms Horton said. “It’s really saying: Can we do this better? Can we do this a bit more efficiently?”
Ms Horton also suggested that The Bahamas could potentially turn its accumulated compliance expertise into an exportable financial services product. She said compliance professionals could potentially provide services to institutions in other jurisdictions, transforming what is generally regarded as a cost of doing business into a revenue-generating opportunity.
“We can see it also as an export opportunity in financial services that we can put out there,” she said. Ms Horton also pointed to duplication in reporting as an area that could be streamlined through greater co-ordination.
“There is also an opportunity here, if we can have a central authority on that, but even more so from an industry standpoint in terms of how we can now reduce what we believe to be a duplication of efforts, particularly around the compliance function, and having to report to the various regulators, to the Government,” she said.
John Rolle, the Central Bank Governor. likewise called for a shift away from overly prescriptive compliance toward a more risk-based and proportionate approach.
He said The Bahamas had historically taken a highly restrictive approach to implementing international standards, and should place greater emphasis on whether its framework is actually effective.
“I think that we have not taken sufficient advantage of proportionality in terms of how we should be applying global standards,” Mr Rolle said. “I think we started off with a very, very restrictive, rigid approach, and we’re trying still to unlearn some of that, but we have to migrate more away from the check-box approach and focus a lot more on how effective this looks in practice.”
Mr Rolle said smaller jurisdictions can end up devoting disproportionate resources to compliance when they fail to tailor international standards to their own risk environment.
“The FATF, for example, and this is something for us to pay attention to,” Mr Rolle said. “They expect that we will tailor standards, but to demonstrate in tailoring the standards, we understand our context and we can justify how we tailor.”
Mr Rolle also called for greater flexibility in the legislative and regulatory framework so that regulators can respond more quickly to changing international requirements without repeatedly having to amend primary legislation.
“We have to find, I think, the right balance both in terms of the framework, and then demonstrate that we understand our environment, and can show how we are tailoring what we know to our context,” Mr Rolle said.
He said regulators should also focus more closely on the effectiveness of institutions’ customer reviews rather than simply ensuring that prescribed procedures have been completed.
“But what should those reviews look like? Is it just having a customer bring in an updated piece of ID, or your account is going to be frozen, or should it be something else?” Mr Rolle said.
“As a regulator, I would like to see it evolve, too, where the amount of prescriptions that we’re putting out there can decrease. And then we can focus more on how effective we are based upon other principles or criteria.”
Mr Rolle also identified cyber risk, particularly those associated with artificial intelligence (AI), as an emerging threat to financial stability. He said the interconnected nature of financial services means cyber incidents can have effects beyond individual institutions, requiring regulators, businesses and government to address the issue collectively.
“And so how we manage the cyber risk cohesively and holistically becomes very important,” Mr Rolle said.
He also stressed the importance of maintaining regulatory competence and credibility as The Bahamas navigates changing international standards. He said regulatory independence and expertise have been important features of The Bahamas’ financial services framework across successive administrations.
Mr Pinder, meanwhile, said the upcoming fifth-round evaluation will make effective implementation by the private sector particularly important.
“First and foremost is ensuring that the industry is constantly prepared and on the same page when the FATF comes for the fifth round next month,” Mr Pinder said.
He said the evaluation will examine not only the Government’s regulatory framework but how requirements are implemented by financial institutions in their daily operations. Mr Pinder also argued that technology and AI should play a greater role in modernising the compliance function, allowing firms to meet regulatory obligations while responding more quickly to clients.
Mr Pinder further argued that regulators themselves have a role to play internationally in defending the sophistication and credibility of The Bahamas’ financial services centre. He said a co-ordinated approach involving Government, regulators and industry should extend beyond the domestic market and into international engagement.
“We always talk about the tripartite approach to financial services in The Bahamas, where we have government, regulator, industry all together, and we do it together,” Mr Pinder said.


Comments
Use the comment form below to begin a discussion about this content.
Sign in to comment
OpenID