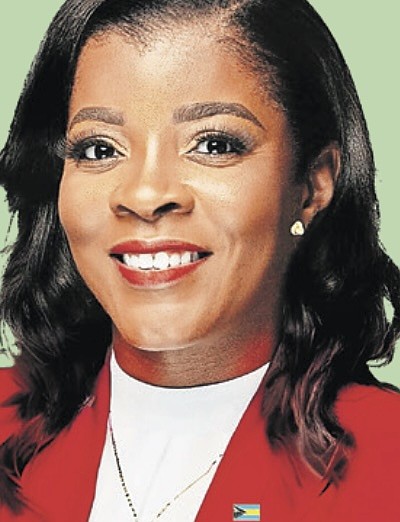
Senator Arinthia Komolafe
By NEIL HARTNELL
TRIBUNE Business Editor
nhartnell@tribunemedia.net
ATTORNEYS are warning against imposing new VAT charges without fixing “a broken system” as an Opposition Senator yesterday urged that the deadline to pay due tax on real estate sales be tripled at a minimum to avoid unfairly penalising mortgage borrowers.
Arinthia Komolafe made her plea for the Government to extend the VAT payment timeline from 21 days to at least 60 days, and no longer than 90 days, from the date the conveyance is executed while joining Bahamian attorneys in calling upon the Department of Inland Revenue and the Government to remedy their own internal deficiencies first.
One attorney, who did not identify herself, told last Thursday’s briefing - where the tax authorities unveiled plans to impose the 5.25 percent interest charge from October 5 if tax is not paid on property sales within 21 days of the conveyance’s execution - that she and her firm have been waiting six months for the Department of Inland Revenue to provide VAT invoices for no less than 33 transactions.
“I can say with certainty we do a lot of conveyancing matters,” the attorney said. “I got back to the Department of Inland Revenue now a list of 33 conveyances waiting for VAT invoices from March to-date. That is the day I put it in within a day of it being signed. I’m delayed just six months waiting on the Department of Inland Revenue. The system is broken, and you are seeking to add fees to a broken system. The question is… to see how we can fix the system.”
Other attorneys voiced similar concerns, one asserting that the 21-day deadline was “pie in the sky” and impossible for many international buyers to meet especially if the parties to the transaction were all overseas in different jurisdictions. This requires conveyances and other key documents to be couriered abroad, signed and then sent back, before being dispatched elsewhere. And these papers also have to be apostilled to verify their authenticity for use in The Bahamas.
Renee Charles, a Department of Inland Revenue official, conceded that this was a legitimate concern. “That is something we do understand might have some challenges,” she agreed of international buyers. “There are things, if you have these concerns, the Department of Inland Revenue does not write the law. I think the international issue may be a legitimate one. That will have to be raised with the appropriate persons and legislators.”
Another attorney, meanwhile, questioned whether the new 5.25 percent interest charge is actually needed given that the tax authorities are already enforcing a 10 percent penalty on conveyances that are not brought forward for stamping, or the payment of due VAT, within 180 days. “No one has an issue with a late fee. The late fee is quite reasonable at six months from the Act,” she said.
“Why does interest preclude the late fee? Interest should only follow the late fee. If the late fee is 10 percent of whatever the VAT invoice is, once the late fee takes effect then the interest should kick-in, not before. It’s not practical. It makes no sense.” Department of Inland Revenue officials sought to distinguish between the two, asserting that the new 5.25 percent charge is for “depriving” the Government of its revenue, whereas the 10 percent is an actual levy.
Meanwhile Mrs Komolafe, arguing that “Bahamians just cannot catch a break” from new fees and penalties, told Tribune Business that the October 5 enforcement deadline needs to be extended as it threatens to automatically impose an extra cost and charge on Bahamian mortgage borrowers through no fault of their own but due to how the conveyancing system works.
Pointing out that the number of Bahamians qualifying for mortgage financing has been declining in recent years, the Opposition Senator warned that the 5.25 percent interest threatens to further disrupt the housing and home ownership market and deter persons from purchasing their ‘piece of the rock’.
Tribune Business revealed on Monday how the new charge was passed into law by Parliament in June 2025 but never enforced until now. Attorneys are warning that the 21-day deadline for payment of due VAT on real estate sales, with the clock running from the moment the conveyance is executed, is “impractical” and will push all mortgage borrowers and international buyers into incurring the Prime plus 1 percent (5.25) interest levy.
Once a conveyance is executed, it is packaged with all other necessary documents, including title opinions and searches, and sent to a bank or other lender if mortgage financing is involved. Bahamian banks typically take two to three weeks, or even longer if they have questions, to review and investigate the transaction before they will release the purchase funds, thus automatically pushing the transaction beyond the 21-day deadline.
Mrs Komolafe, having been involved in real estate transactions personally, as well as working for mortgage-lending banks, representing clients as an attorney and holding office in the public sector, told this newspaper her experience gave her a good insight insight from all sides as to what is required in “the due diligence, the document requirements, the approvals process and how involved it is and the bureaucracy you are dealing with”.
“I understand all sides of the argument,” Mrs Komolafe said. “I don’t have a problem with enforcement of the law, but we need common sense to prevail. The cut-off deadline is unrealistic and unreasonable; anyone involved in real estate transactions understands that. It appears the Government and Department of Inland Revenue are disconnected from reality.
“I don’t believe buyers should be penalised for inefficiency in the processes and procedures beyond their control. The Department of Inland Revenue needs to get its house in order and address the bottlenecks and inefficiencies in its purview.”
Department of Inland Revenue officials, on the conference call with attorneys last week, said the tax authority would deduct the time a conveyance spends with it for review or challenge from the 21-day period’s calculation. However, Mrs Komolafe argued that this pledge needs to “codified in some legislation or rule. We don’t want ad hoc policies implemented from time to time. We want consistency, transparency and to know what we are dealing with.
“We don’t want to penalise or frustrate those that qualify [for mortgages] and burden them with extra cost,” she added. “There needs to be some consultation with stakeholders so that we can come to an agreement on this.”
The Senator described her proposed 60-day or 90-day timelines, which would replace the existing 21 days, as “reasonable” given the numerous issues impacting property titles in The Bahamas and the absence of a digital system for processing transactions.
“You have to send documents away for these transactions to be executed,” Mrs Komolafe added. “In the absence of a digital system, you cannot impose strict timelines or deadlines with the paper-based system we have. It’s just not practical.”
Parliament, in May and June 2025, amended section 47A of the VAT Act with effect from July 1 that year to provide for the new interest charge that the Department of Inland Revenue has held off enforcing until now.
“To be clear, all right-thinking Bahamians support the enforcement of the law which has been in effect since July 2025. However, a common sense approach must be adopted. The enforcement of this provision in its current from could serve as an impediment and make home ownership more difficult for some,” Mrs Komolafe warned in a statement.
“Economic reports show that while there is high liquidity in the [banking] system, a lot of Bahamians cannot qualify for mortgages and/or afford the closing costs associated with real estate transactions. The decision to enforce this fine ignores the practical realities of real estate transactions and will ultimately punish purchasers of real estate by driving up costs.
“In simple terms, the penalty is likely to be incurred by a majority of buyers because of the typical requirements of real estate transactions involving authentication of documents, financing requirements, fund disbursements and regulatory approval, which take time,” she added.
“Real estate is already costly and the addition of even more monetary fines to existing taxes will only push real estate beyond the reach of many Bahamians and make it difficult to do business in our country. Buyers should not be penalised for circumstances beyond their control.
“It is clear that the implementation of this penalty has not been well thought out, but the Department of Inland Revenue still has an opportunity to change course. The implementation of the penalty should be postponed while stakeholders are engaged in meaningful discussions,” Mrs Komolafe argued.
“The Davis administration should consider moving the trigger clause from 21 days to 60 days, and no more than 90 days, to account for the logistical realities involved in real estate transactions. Additionally, the Government should engage stakeholders with a view to receiving confirmations on the establishment of an escrow account and the deposit of projected VAT payments with an assurance that the tax will be remitted upon completion of the conveyancing transaction.
“Finally, the undertaking provided that persons will not be penalised for delays by the Department of Inland Revenue itself must be embedded in statute or enforceable rules to ensure accountability, predictability and consistency….. The continued absence of a digital registry makes it nonsensical to impose deadlines that do not reflect the current realities of a paper-based system.”
One attorney, speaking on condition of anonymity, said of Mrs Komolafe’s proposed timelines: “I think that’s reasonable. Ninety days would be preferred, and 60 days would be the minimum, and maybe some flexibility for whatever the time period is that they reach; if there’s an ability to have it extended in extenuating circumstances.
“We’re not going to think of every situation. If there’s some flexibility in legislation for the time to be extended, but you have to justify it and make the case that it is reasonable.”


Comments
Use the comment form below to begin a discussion about this content.
Sign in to comment
OpenID